 Written by Nicki Price, CEO
In short: A home in a Costa Blanca flood zone is still insurable and still mortgageable in 2026, because Spain's state reinsurer, the Consorcio de Compensación de Seguros, covers flood (inundación) and DANA damage on every ordinary home policy for a small fixed surcharge, not a market-priced premium. What flood risk really changes is your buildings cover being treated as mandatory by the lender, a sharper bank valuation (tasación), and in high-exposure spots a private insurer loading or declining the optional extras. Expect a standard Costa Blanca home policy of roughly €250-€600 a year, with the Consorcio surcharge adding only a few tens of euros.
The October 2024 DANA that devastated parts of Valencia province made every buyer on the Costa Blanca, Costa Cálida, Costa del Sol and Costa Almería ask the same question: if the area floods, can I even buy here? The honest answer is yes, but you need to understand how Spain splits the risk between the Consorcio, your private insurer and your bank. This guide walks through all three.
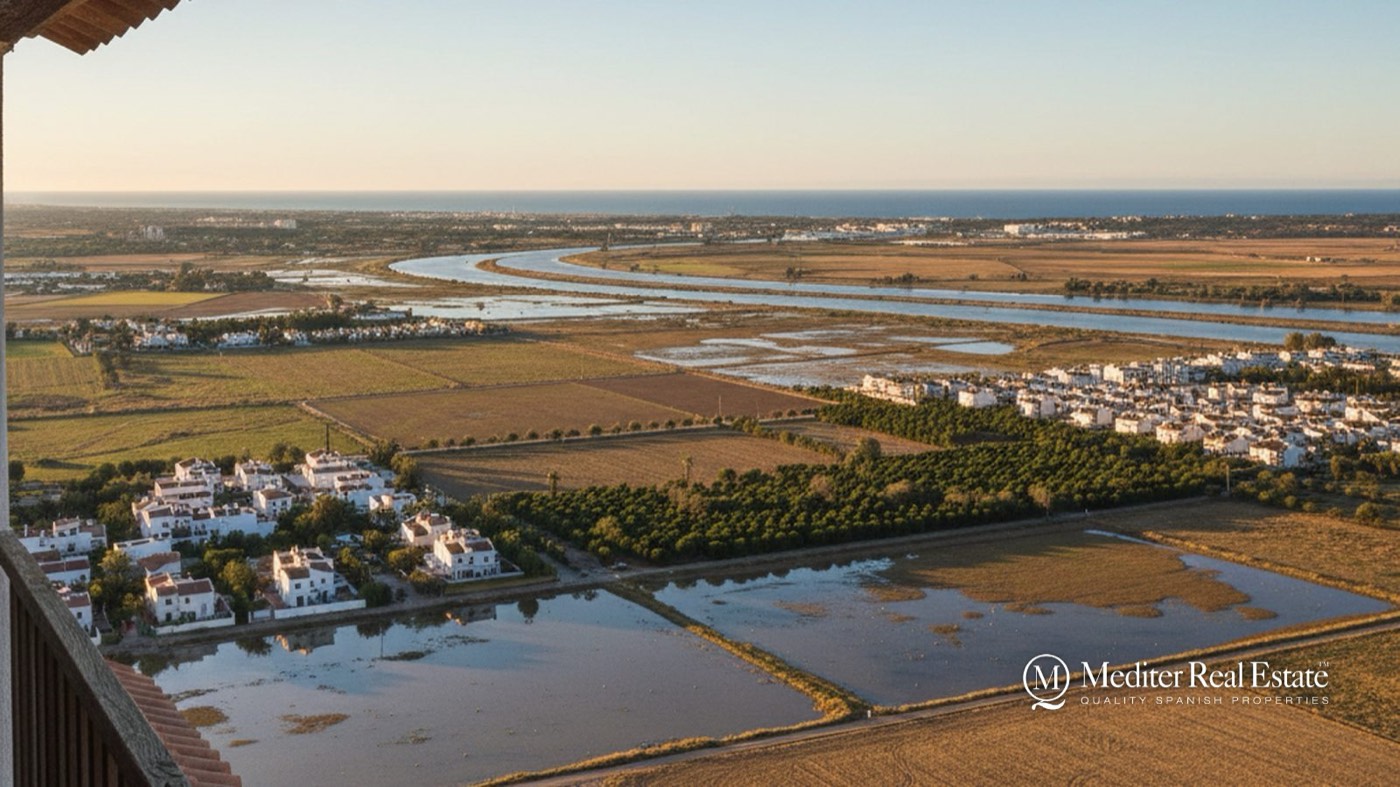
A DANA (Depresión Aislada en Niveles Altos, the "cold drop") is an isolated high-altitude depression that can dump a month of rain in hours on Spain's Mediterranean coast, typically in autumn. It matters because the south-eastern costas, especially the low-lying Vega Baja around Orihuela, Rojales, Dolores and Guardamar on the Costa Blanca South, and ramblas (dry riverbeds) across the Costa Cálida and Costa Almería, concentrate exactly the flat, built-up, river-fed terrain where water has nowhere to go.
The flood risk is not evenly spread. Hillside towns such as San Miguel de Salinas or Hondón de las Nieves sit well above the plain, while a ground-floor apartment beside a rambla is a different proposition entirely. Checking the specific plot, not the region, is the whole point.
Flood and DANA damage is covered by the Consorcio de Compensación de Seguros as an automatic add-on to any home insurance policy with fire/multi-risk cover, you do not buy it separately and no private insurer can refuse it. The cost is a small statutory surcharge calculated on your sum insured, not a risk-rated premium, so it does not balloon just because your home is in a flood zone. Your total annual cost is therefore driven mostly by the ordinary private policy, typically €250-€600 a year on the Costa Blanca depending on the size and value of the home.
| Region | Ordinary policy (buildings + contents) | Consorcio surcharge (flood/DANA, earthquake, storm) | Flood exposure profile |
|---|---|---|---|
| Costa Blanca (Alicante) | €250-€600 | A few tens of € (fixed % of sum insured) | High on Vega Baja plain, low on hillside towns |
| Costa Cálida (Murcia) | €230-€550 | Same statutory basis | Rambla/flash-flood pockets inland and near Mar Menor |
| Costa del Sol (Málaga) | €260-€620 | Same statutory basis | River mouths and steep urbanisations |
| Costa Almería | €220-€520 | Same statutory basis | Dry ramblas prone to flash flooding |
The key point most competitor articles miss: the Consorcio surcharge is set nationally by the Agencia Tributaria-collected mechanism and is the same statutory rate whether your home is on a hill or a floodplain. Where private insurers do push back is on optional extras, temporary alternative accommodation, swimming-pool equipment, garden landscaping, which they can load or decline in high-exposure postcodes.
The Consorcio de Compensación de Seguros covers "extraordinary risks", flooding, DANA-type torrential rain, storms with winds over 120 km/h, earthquakes, and certain other catastrophic events, on any Spanish property that holds a valid home insurance policy. Compensation is paid directly by the Consorcio once your event is declared, regardless of which private insurer wrote your policy.
Because cover is automatic and non-refusable, a flood-zone property on the Costa Blanca is never "uninsurable for flood" the way it can be in some other countries. That is the single most reassuring fact for nervous buyers after 2024.
Yes, indirectly but materially. Spanish lenders do not usually refuse a mortgage purely because a home sits in a zona inundable, but flood risk feeds into two things they care about: the tasación (bank valuation) and their requirement that you hold buildings insurance for the life of the loan. A valuer who flags flood exposure can return a lower figure, which cuts the amount the bank will lend because they lend against a percentage of that valuation, not your purchase price.
Non-resident buyers typically borrow against 60-70% of the lower of price or valuation, so a flood-dampened tasación directly shrinks your loan and raises the cash you must bring. If you are financing, read our guides on the non-resident mortgage and on how a tasación compares with the asking price before you commit.
Before you fall in love with a plot, check the official flood-hazard mapping: the national Sistema Nacional de Cartografía de Zonas Inundables (SNCZI) maintained under the Ministerio and the regional PATRICOVA flood plan for the Comunidad Valenciana show which zones are mapped as flood-prone and at what return period (10, 100 or 500 years). The Costa Cálida uses Murcia's own flood planning and Andalucía its own, but the SNCZI covers all four costas.
Also pull the nota simple and ask your lawyer to cross-check the Catastro location against these maps. On the coast itself, flood risk overlaps with the public-domain setback rules we explain in our coastal flood and Ley de Costas guide and the setback-zone guide, two separate issues that often appear together on beachfront plots.
It can. A documented flood history or a mapped high-risk zone tends to soften prices and lengthen selling times, and it is legitimate leverage when you negotiate on the Costa Blanca. Against that, demand for well-located coastal homes remains strong, and buyers increasingly accept that Consorcio cover protects the fabric of the building. The practical risk is not that you cannot resell, it is that a future buyer's bank valuation could be cautious too.
Mediter Real Estate currently has 8,429 properties for sale across Costa Blanca South, Costa Blanca North, Costa Cálida, Costa del Sol, Costa de Almería and Mallorca. A large share of our Costa Blanca South stock sits in the Vega Baja towns, Torrevieja, Orihuela Costa, Rojales, Guardamar del Segura, Los Montesinos and San Fulgencio, where elevation and drainage vary street by street, which is exactly why we encourage buyers to check the specific plot rather than judge a whole town. Hillside options such as San Miguel de Salinas and Hondón de las Nieves sit well above the plain. Browse the full searchable stock at mediter.com/properties.
Flood exposure is a local, not a regional, verdict, but the pattern differs by coast. The Costa Blanca South's Vega Baja is the flattest and most river-fed of the four. The Costa Cálida and Costa Almería share a flash-flood profile driven by dry ramblas that fill in minutes during a DANA. The Costa del Sol's risk concentrates at river mouths and on steep urbanisations where run-off accelerates. For a wider comparison of the four coasts see our four-coast comparison, and for budgeting the whole package our cost-of-living guide.
No private insurer can exclude the flood and DANA cover provided through the Consorcio de Compensación de Seguros, it is automatic on any valid home policy. They can, however, decline or load optional extras in high-risk postcodes.
It is a small fixed statutory percentage of your sum insured, usually only a few tens of euros a year, and it is the same rate regardless of whether your home is in a flood zone or on a hill.
Rarely a flat refusal. More commonly a valuer flags flood exposure, the tasación comes in lower, and the bank lends a smaller amount against that valuation, meaning you bring more cash.
Yes. Lenders require buildings cover for the life of the loan, and that policy automatically includes Consorcio flood and DANA protection. Some banks ask to be named as beneficiary.
Check the SNCZI and PATRICOVA flood maps, review the nota simple and Catastro location with your lawyer, and ask neighbours and the comunidad directly, local memory of the 2024 DANA is detailed and reliable.
No. Resale ITP on the Costa Blanca is 9% for deeds signed from 1 June 2026 (Ley 5/2025), and new-build buyers pay 10% IVA plus 1.4% AJD in the Comunidad Valenciana, flood risk affects insurance and valuation, not these rates.
Flood risk should inform your choice, not frighten you away from a coast you love. Mediter Real Estate can show you which streets and urbanisations sit high and dry, help you read the flood maps and tasación, and line up insurance quotes before you sign. Get in touch at info@mediter.com or +34 744 719 499, or visit us at Calle Caspio 2, C.C. Lomas de Cabo Roig, Orihuela Costa, to find the right property on the Costa Blanca, Costa Cálida, Costa del Sol or Costa Almería.
We use what you tell us here only to answer you. Privacy
We use cookies the site needs to work. With your OK we also use Meta (Facebook) cookies to measure our ads and show you homes like the ones you looked at. Google Analytics cookies, also only with your OK, count visits and show us which pages help.
Cookie policy